

The number that caught my attention in Anthropic’s S-1 was 2.08.
In Q2 2026, Anthropic generated $2.08 of revenue for every dollar of compute and infrastructure expense. In Q1 2025, it generated just $0.40. That is a 5.2× improvement across six reported quarters.
This gets at a question I keep coming back to in the AI trade: can the value created by intelligence scale faster than the infrastructure required to deliver it?
Anthropic’s filing provides meaningful evidence that it can. It also shows why improving operating economics and enormous infrastructure spending can coexist.
My thesis is that the shift toward autonomous workflows expands how much useful work AI can perform, while improvements in compute efficiency make more of that work economically viable. The opportunity is substantial. The unresolved question is how much of the resulting value Anthropic can retain after competition, reinvestment, and the cost of capital.
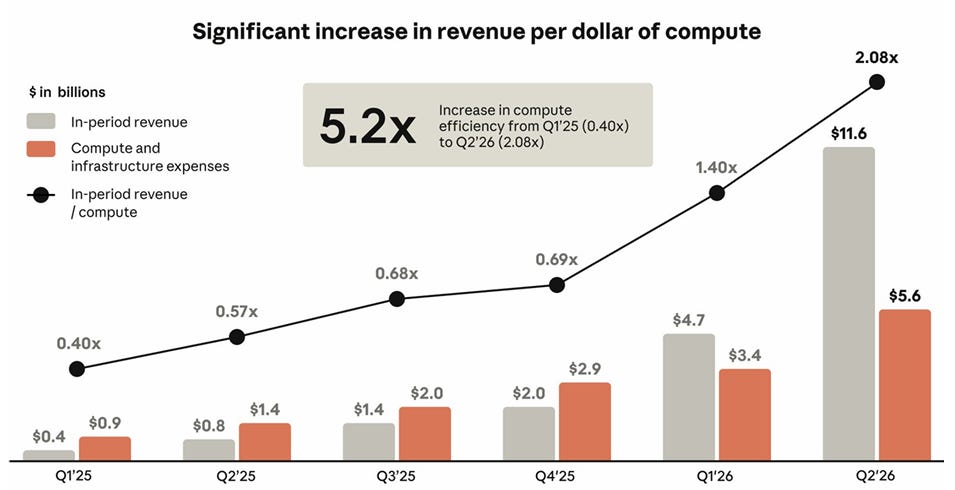
What the 5.2× improvement actually tells us
The underlying numbers are striking. Quarterly revenue increased from $376 million to $11.555 billion between Q1 2025 and Q2 2026. Compute and infrastructure expense increased from $944 million to $5.558 billion. Revenue grew roughly 30.7× while that expense grew roughly 5.9×. [1]